
THIRD QUARTER 2026
Letter to Investors
November 3, 2026

My fellow investors,
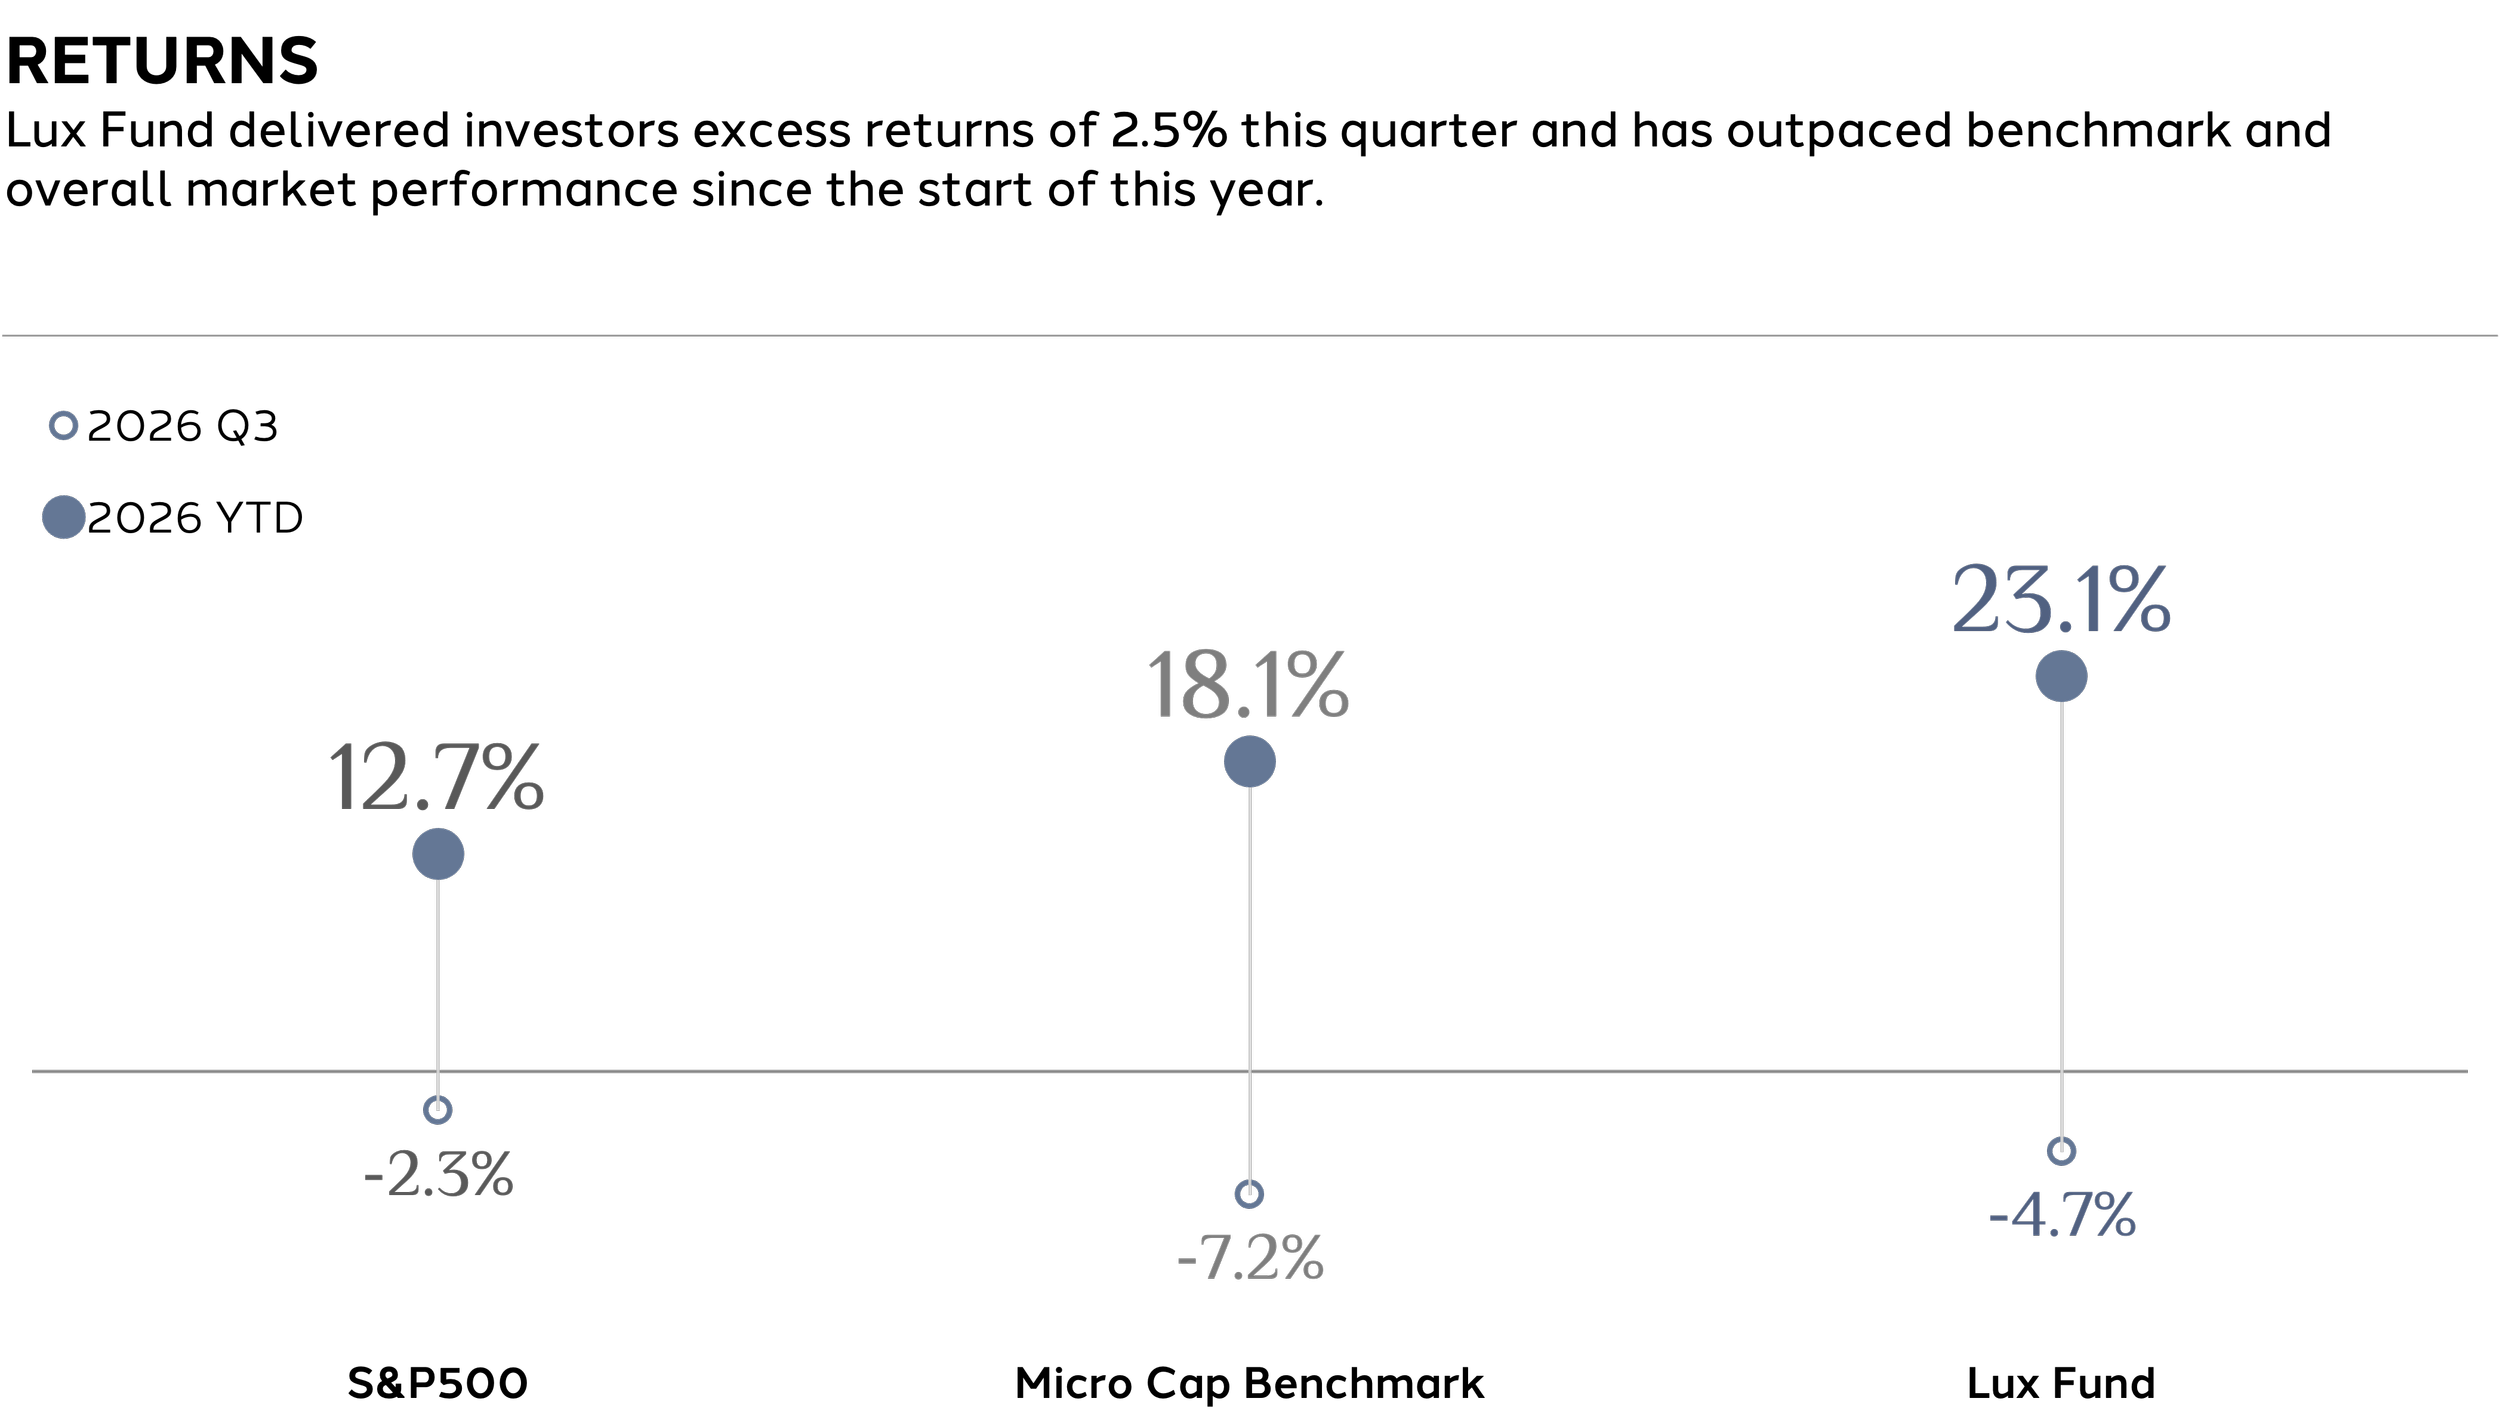
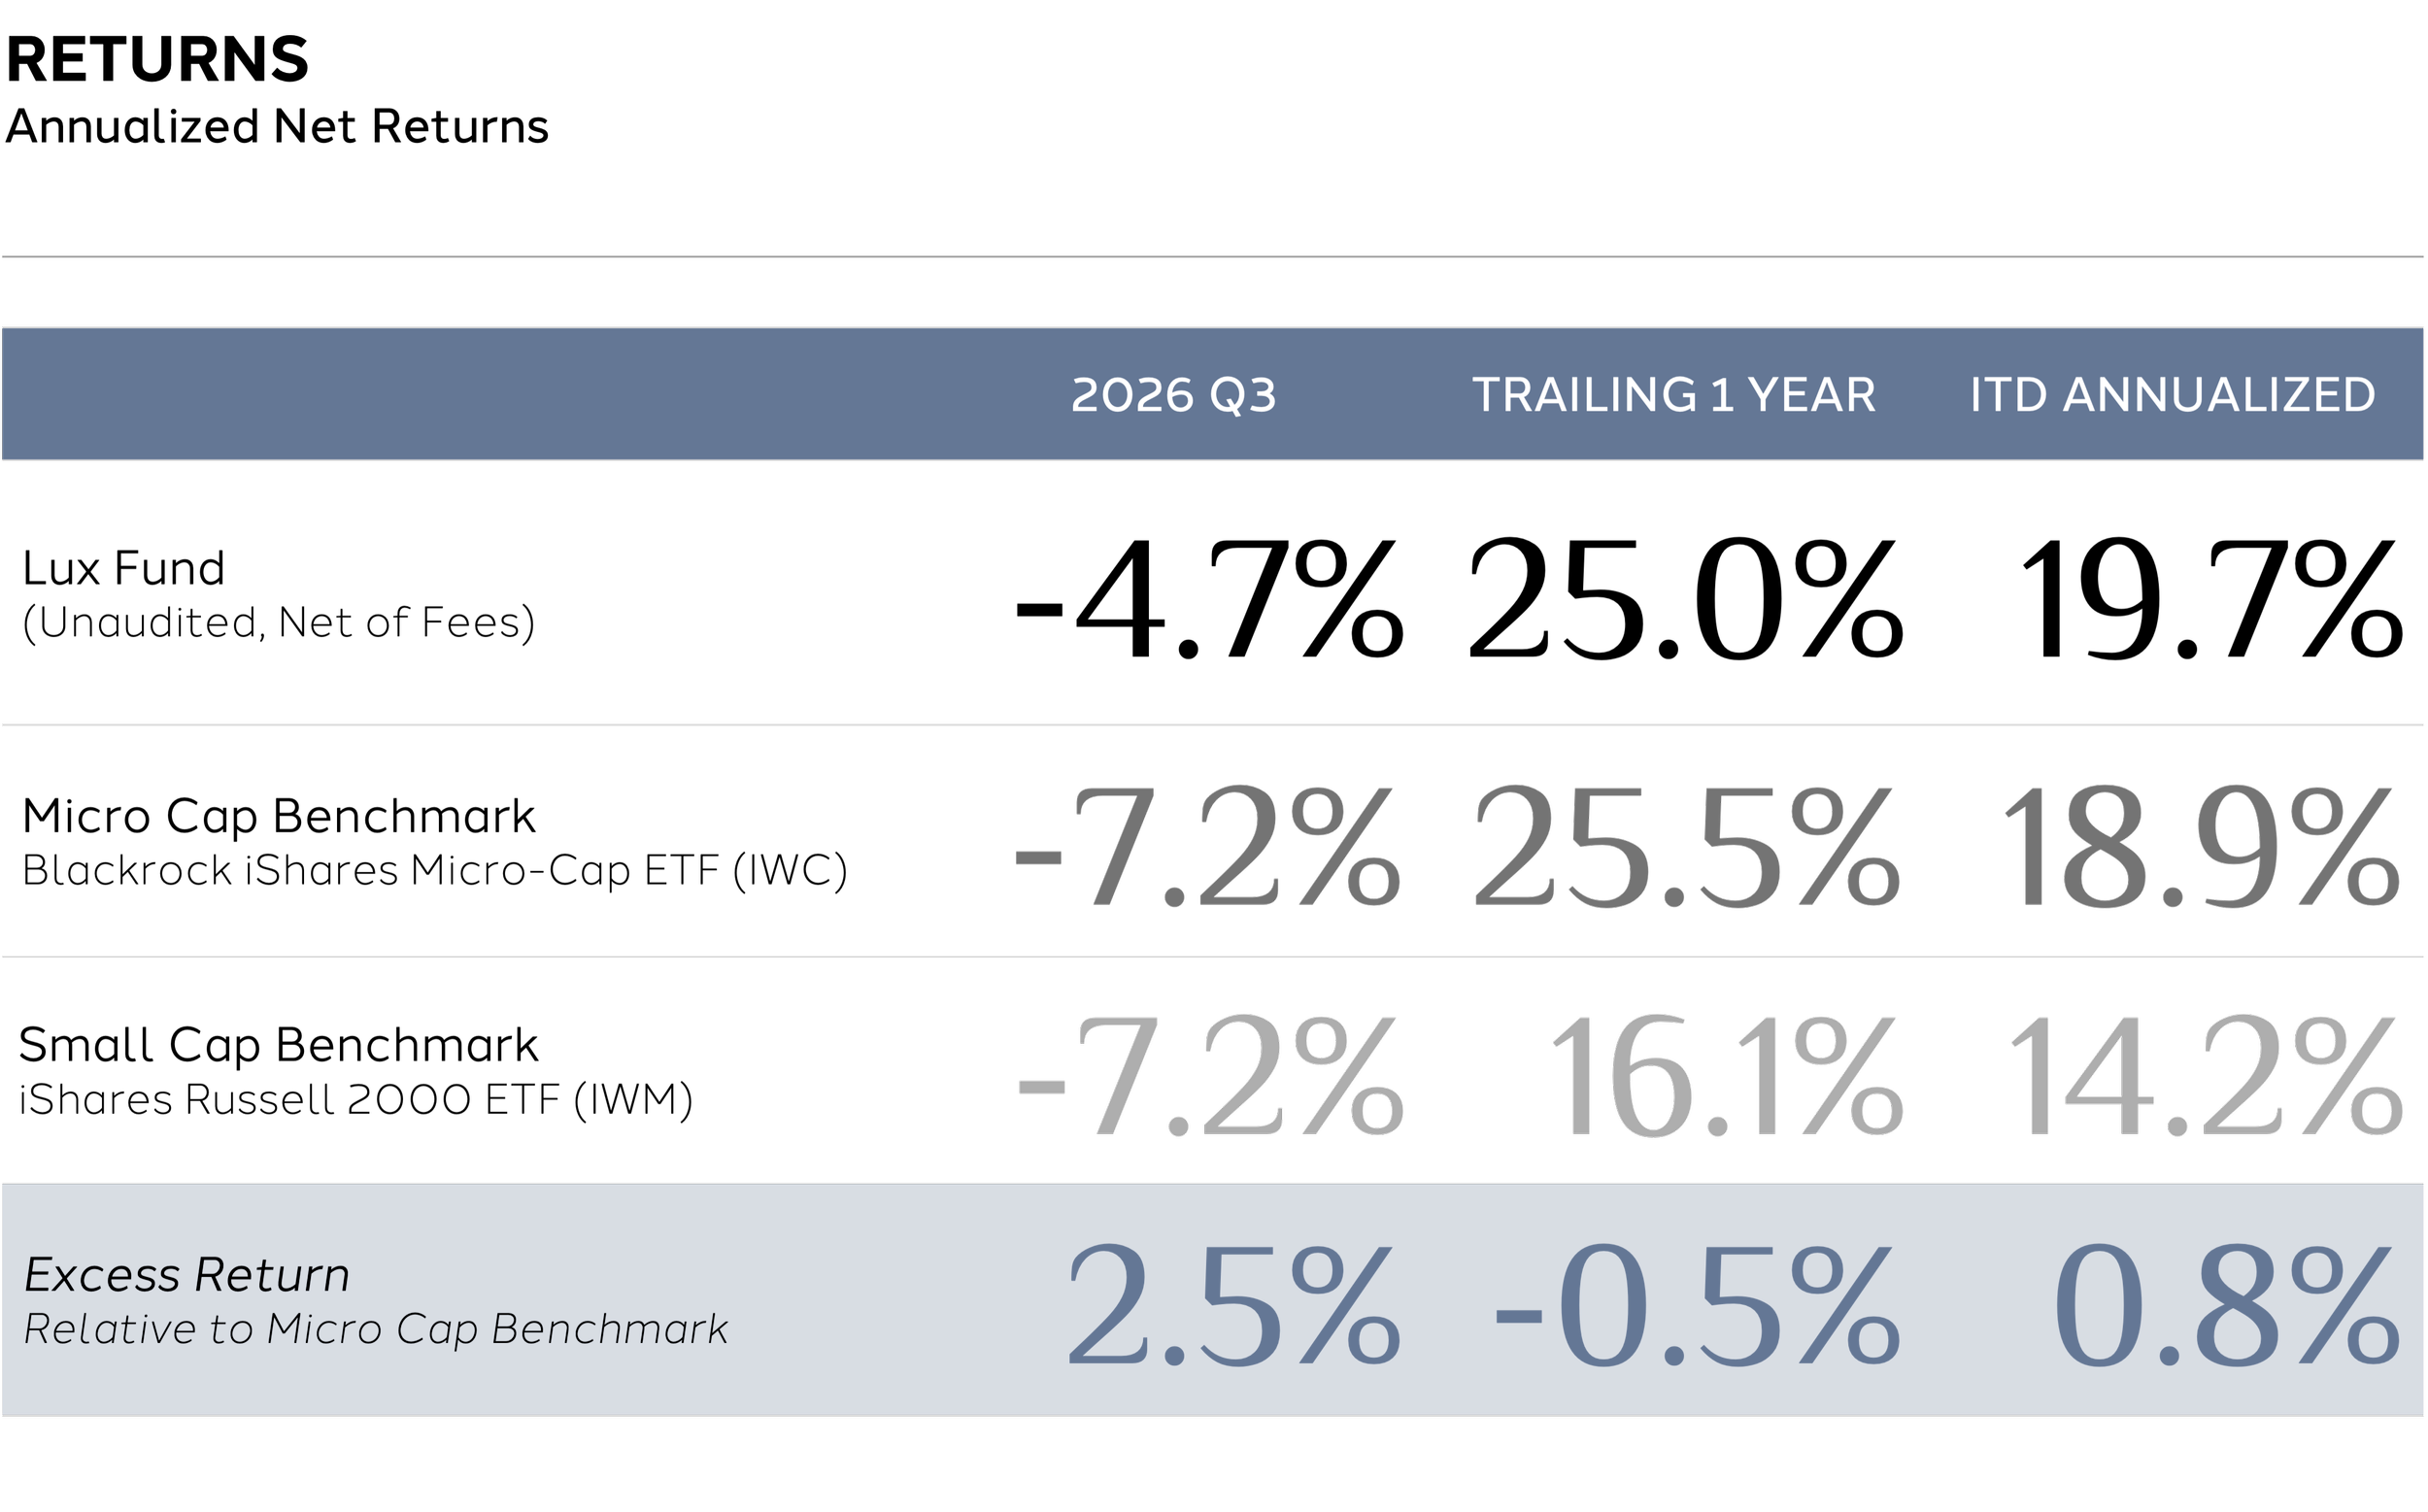
Lux Fund declined 4.7% during the third quarter of 2026, protecting its investors against a broader sell off in the asset class measured by Blackrock’s iShares Micro-Cap ETF and iShares Russell 2000 ETF which each declined 7.2%. Consistent with our balanced portfolio strategy, the Fund's sector diversification contributed to its relative resilience amid weakness in the micro and small cap market.
Year to date, Lux Fund has appreciated 23.1% compared to the iShares Micro-Cap ETF’s 18.1% and the S&P500’s 12.7%. We are encouraged by the Fund's results, which reflect the balance between growth and risk management that we seek to achieve for our investors.
In prior letters, we provided a quantitative framework supporting our view that the current market is at a crossroads, and that now is a critical time to consider micro cap exposure within your total portfolio. This quarter's Portfolio Outlook turns to examples of how the Fund identifies companies in niche markets that can repeatedly capitalize on attractive business opportunities that are "too small" to move the needle for larger companies.
The thesis driving our underlying investments mirrors that of your investment in the Fund: find overlooked opportunities that are passed over not for lack of merit, but for lack of materiality to larger enterprises, and buy them at attractive relative valuations.
In recent years, leading RIAs and institutional investors have focused on private equity, private credit, digital currencies, and most recently private infrastructure. The lack of attention to small public equities is what gives us the opportunity to continuously find overlooked assets generating strong returns on equity and to assemble them into a diversified portfolio.
We sincerely appreciate the trust you continue to place in Gurnee Group. Thank you for the opportunity to serve you.
Sincerely,

J.P. Gurnee, CFA
Portfolio Manager
jp@gurneegroup.com | 989.513.0082
-
Portfolio Outlook
We see ample opportunity in today’s market, as the majority of the investment industry remains focused on flashing lights: private equity, private credit, digital currencies and private infrastructure.
-
Position Changes
Our investment process emphasizes investing in profitable businesses at valuations that permit future appreciation, which we believe will result in long lasting success for our investors.
-
Performance Summary
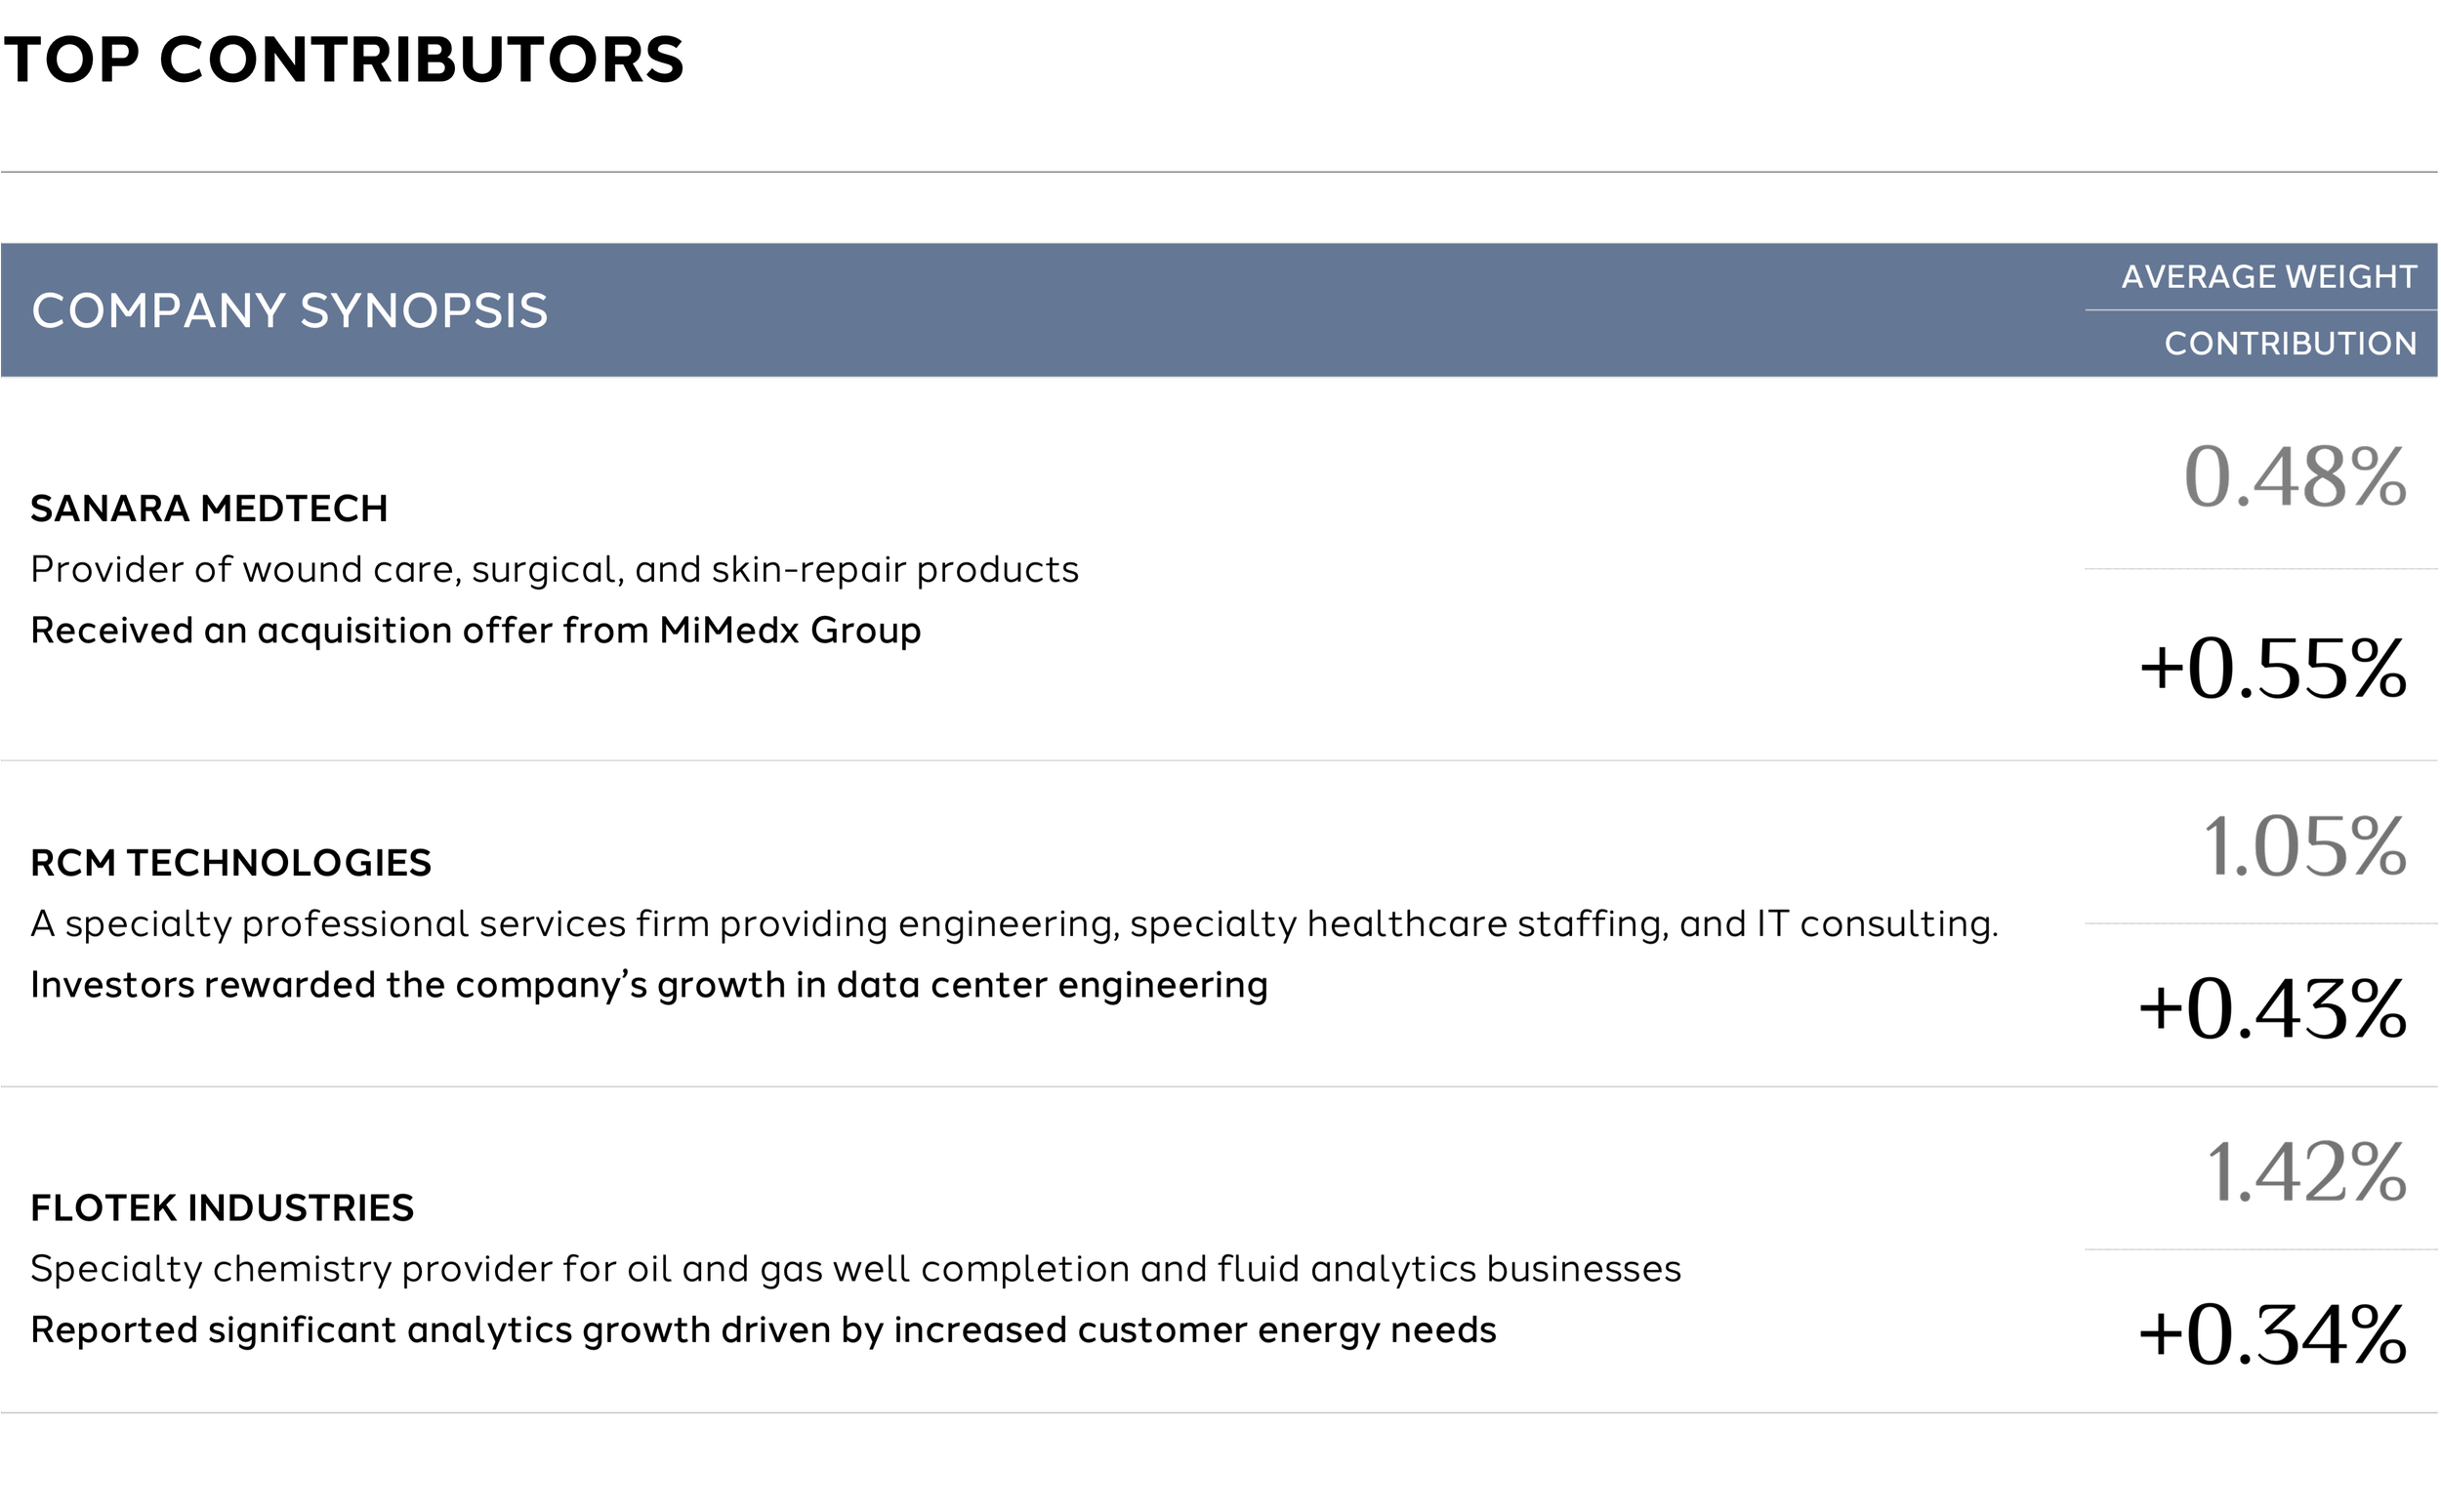
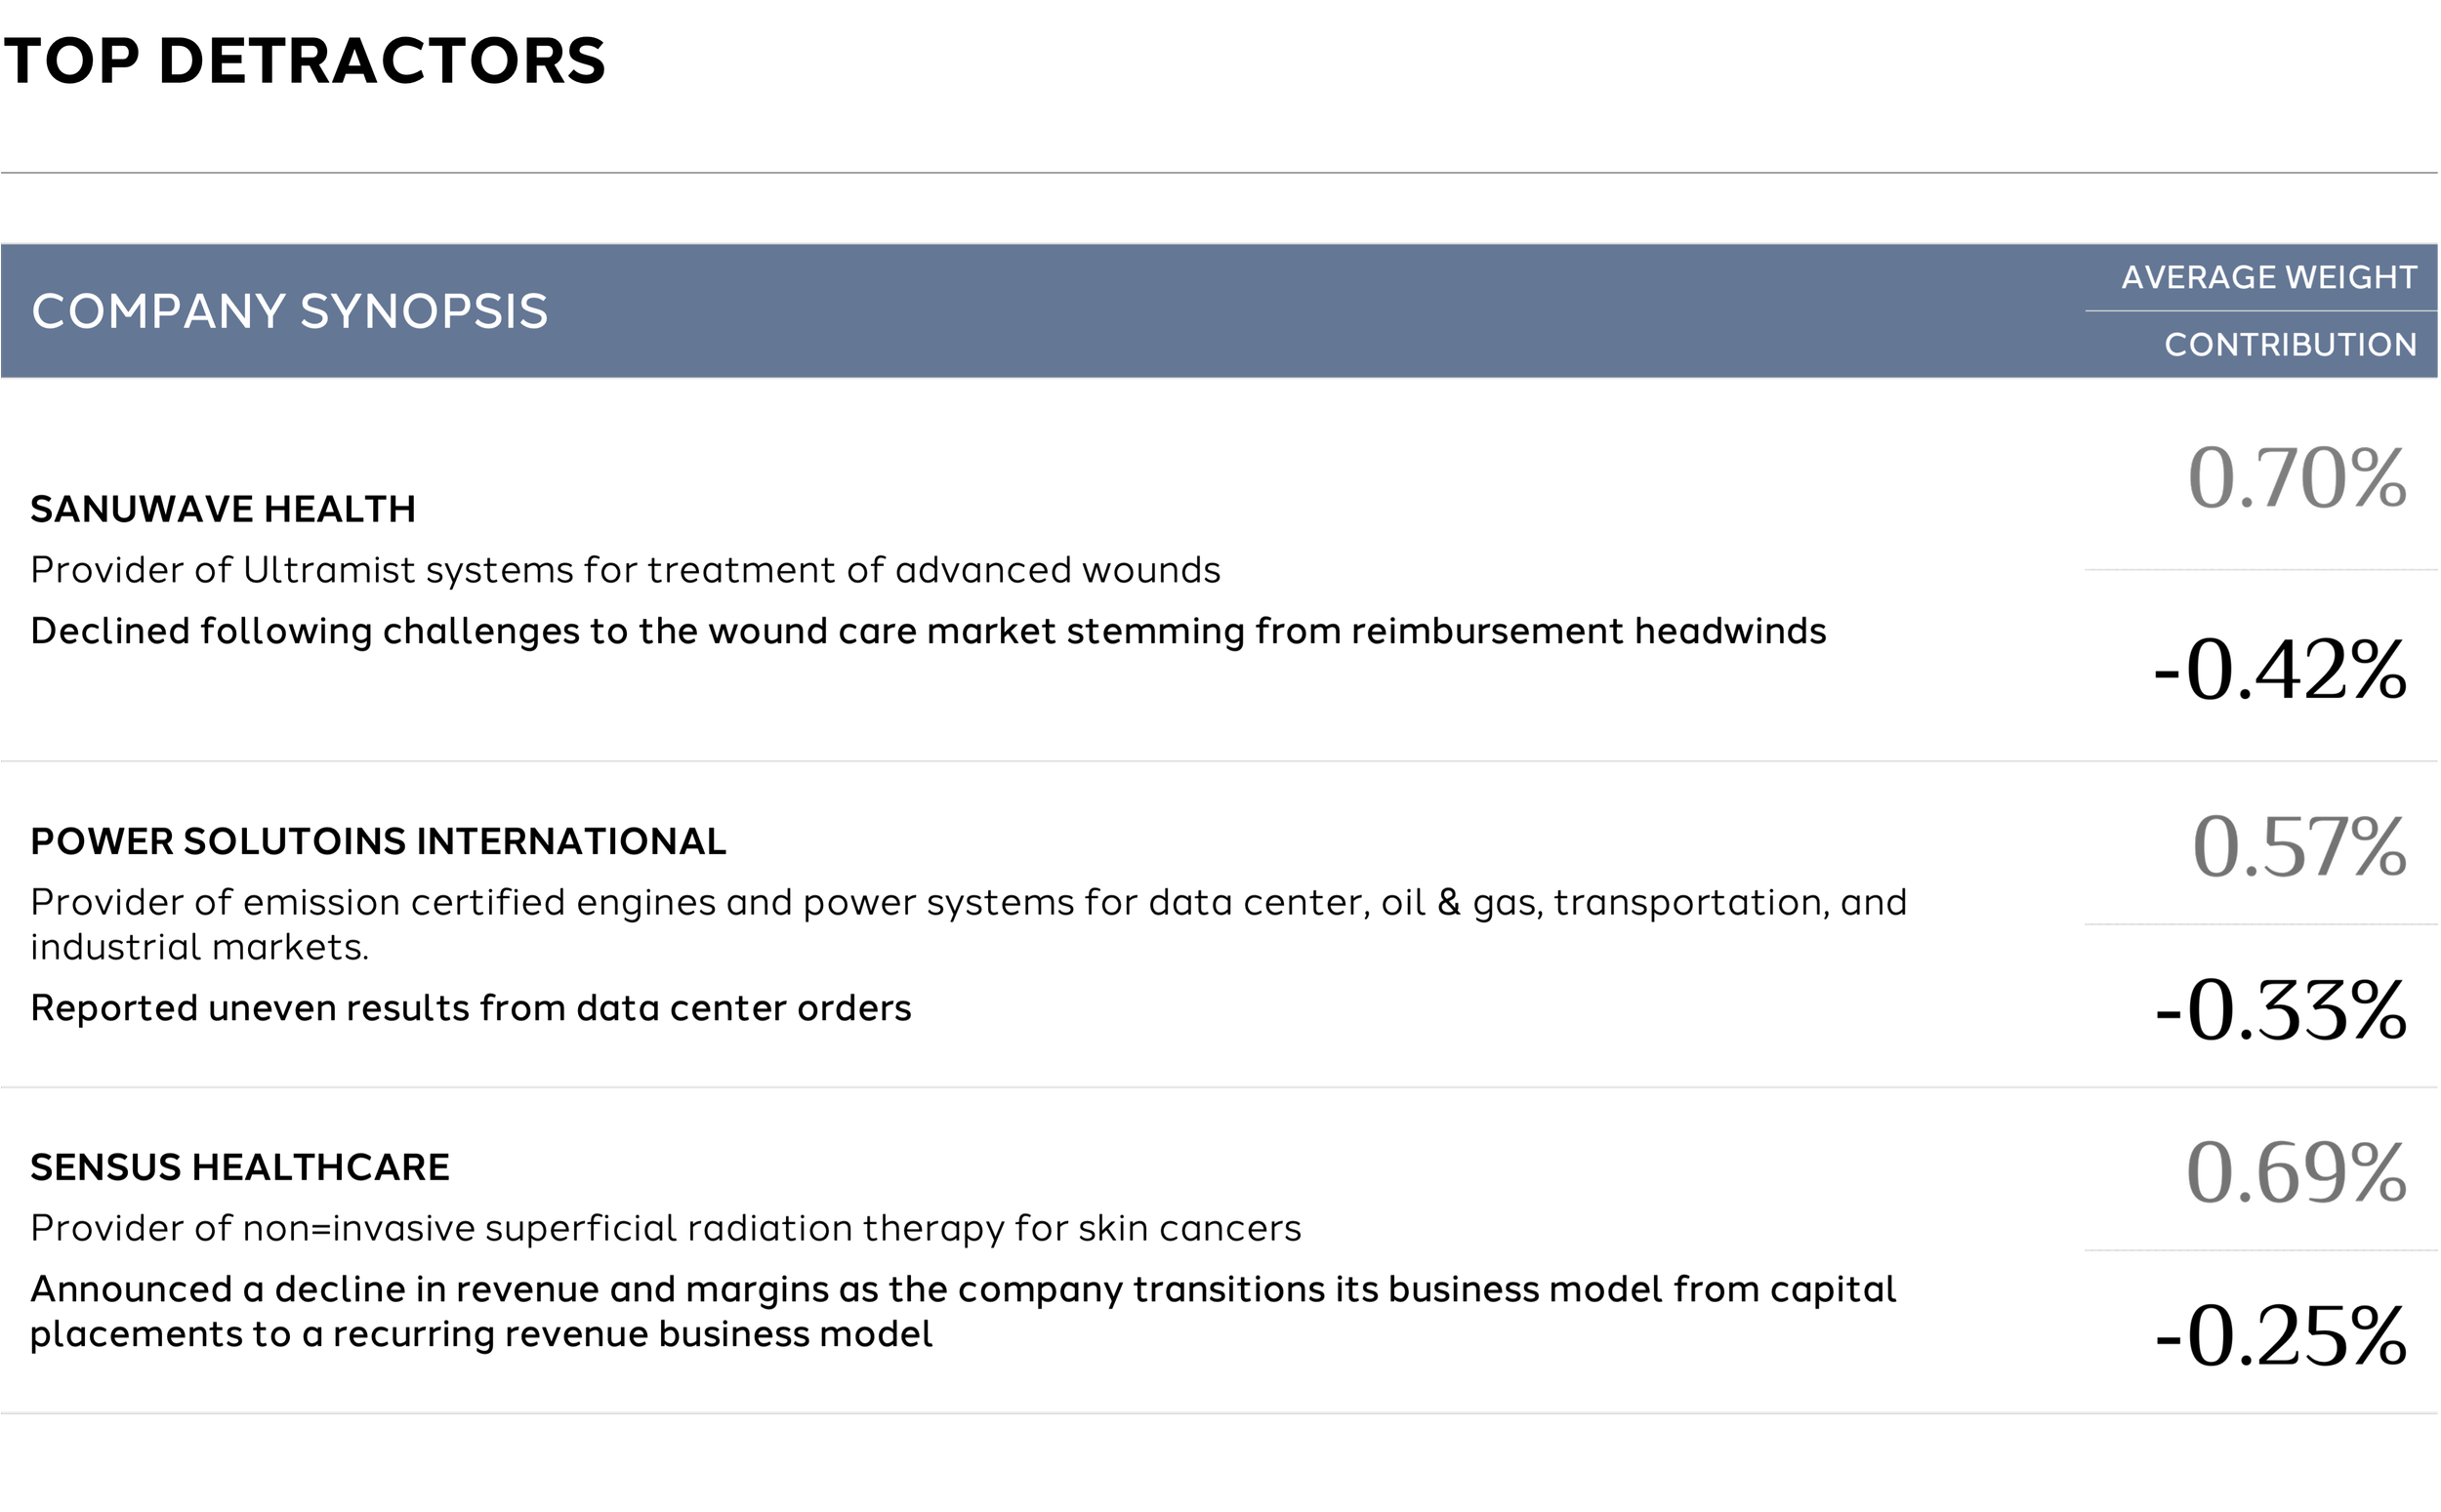
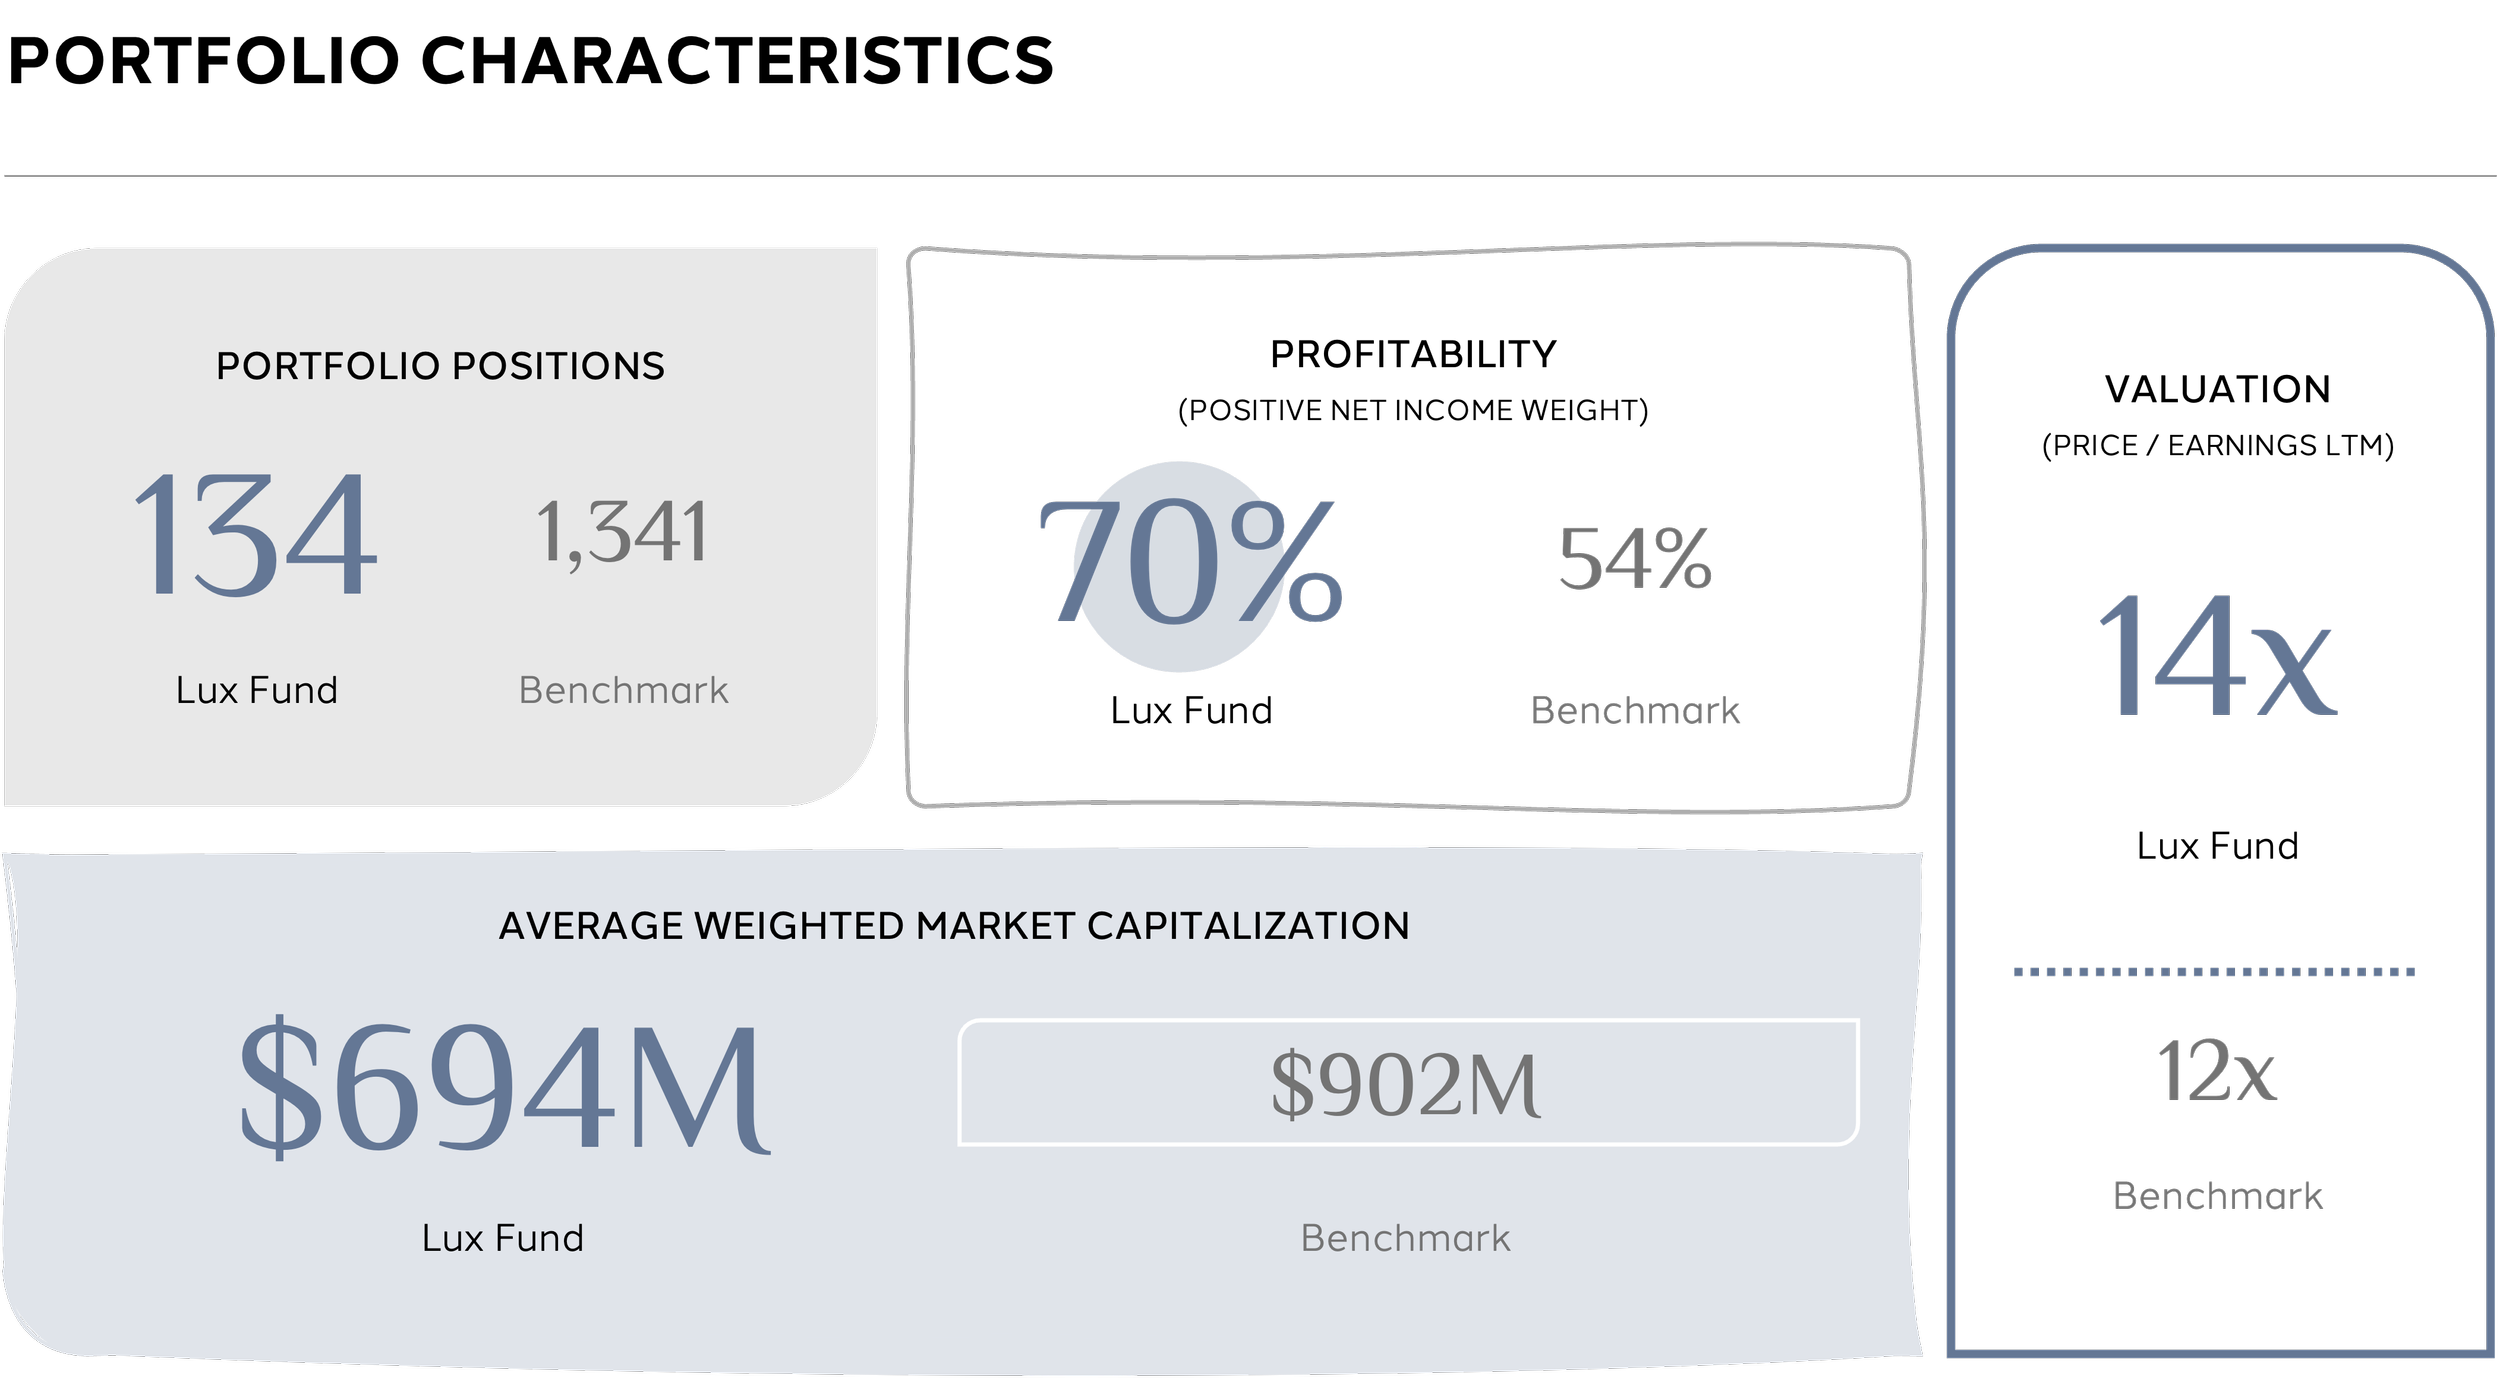
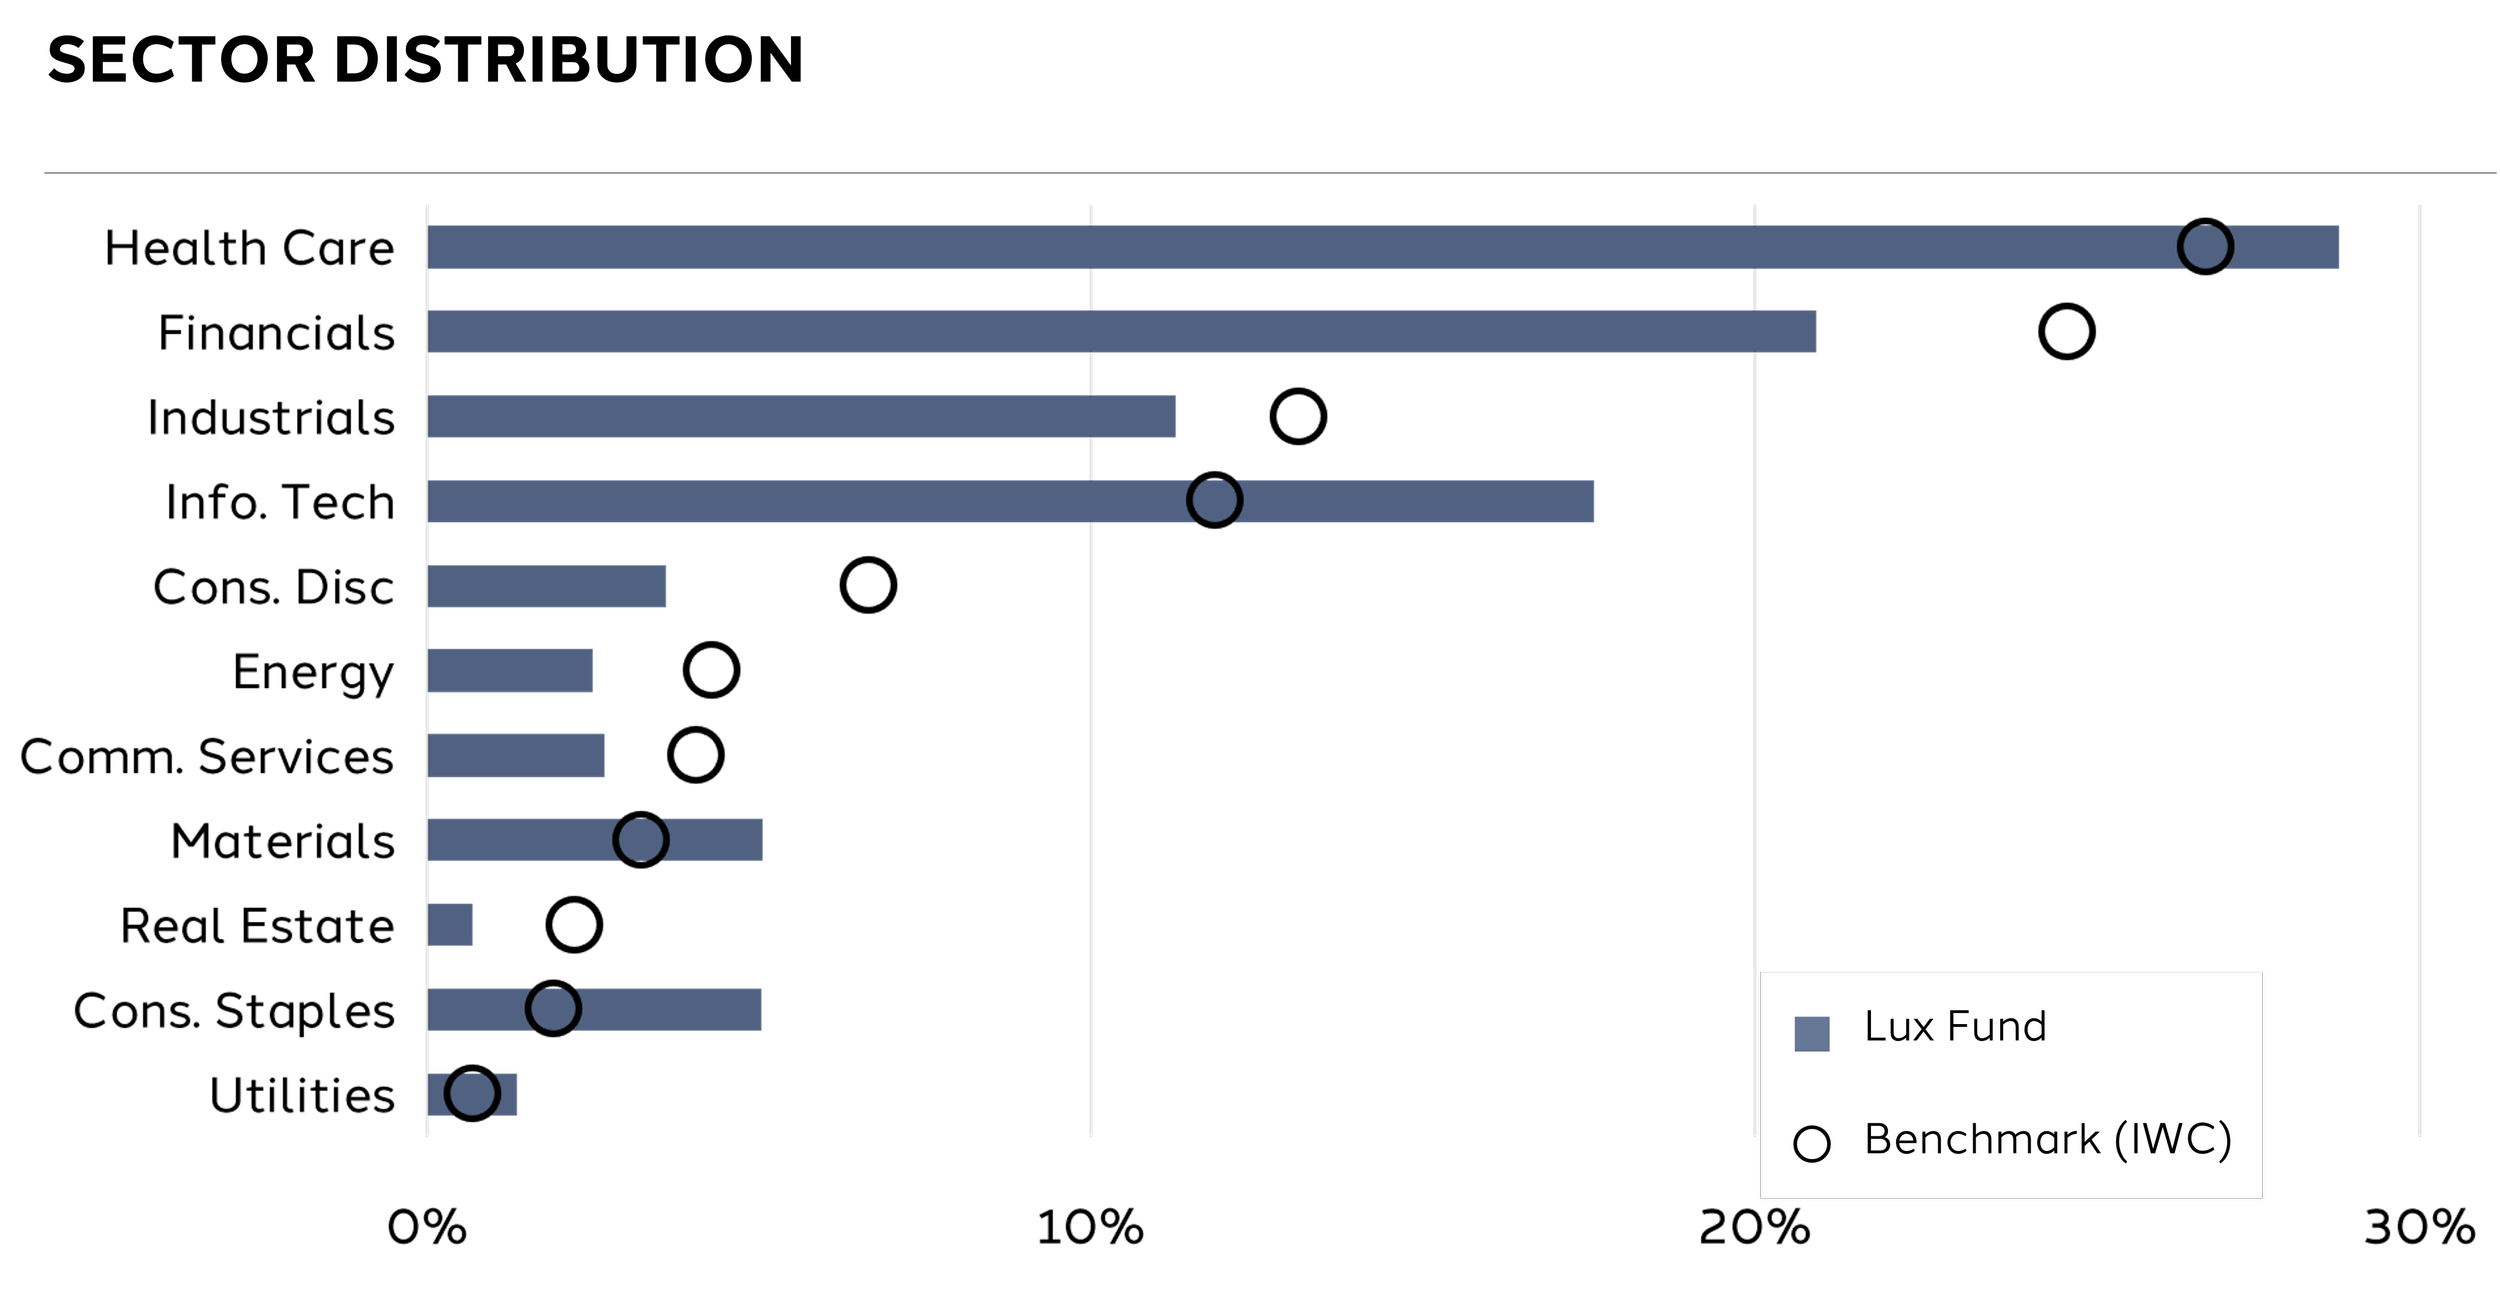
View quarterly results including returns, top contributors and detractors, and portfolio characteristics.
Portfolio Outlook
The thesis driving our underlying investments mirrors that of your investment in the Fund: find overlooked opportunities that are passed over not for lack of merit, but for lack of materiality to larger enterprises, and buy them at attractive relative valuations.
We see ample opportunity in today’s market, as the majority of the investment industry remains focused on flashing lights: private equity, private credit, digital currencies and private infrastructure.
The Fund’s holdings are informed by a quantitative process which alerts our investment team to material business changes for the 2,000+ company investable universe on a daily basis. Our investment team then conducts a qualitative review and assesses the impact of identified changes for the most promising candidates. The Fund holds investments in over 100 companies. We welcome the opportunity to discuss any of these investments in detail. Here are two examples:
-
The Fund has held a position in Pennant Group since 2023. Pennant operates home health and hospice clinics across the country and has delivered double-digit organic volume growth with expanding margins over the last few years. In the past year, Pennant benefited from a unique transaction that we believe was relatively unnoticed by the investment community. In 2025, United Health, the largest healthcare services company in the world, acquired Amedisys, a Pennant competitor, for about $3 billion, or roughly 13x EBITDA. As a condition of this acquisition’s approval, the Department of Justice required United Health to divest certain Amedisys assets because of antitrust concerns. Pennant stepped in and acquired 54 home health and hospice locations for about $150 million. The locations were generating roughly $200 million of revenue and $20 million of EBITDA, implying a purchase multiple of about 7.5x, or roughly 40% below what United Health paid for Amedisys. The acquired locations are concentrated in Tennessee, a certificate-of-need state with meaningful barriers to new competition, which we believe makes them relatively valuable among the Amedisys portfolio. Pennant believes they can lift margins on these sites toward its 18% company target, which would reduce the effective purchase multiple from 7.5x EBITDA to about 4x EBITDA.
In short, our Fund invested in a company which bought assets from one of the largest companies in the world at a roughly 40% discount, and potentially as much as a 70% discount if margins improve as the company intends, because the large company was compelled to sell and had little incentive to optimize assets that were immaterial to its enterprise. This is the kind of inefficiency we seek and is present among the asset class to discerning eyes.
-
The Fund has been invested in shares of Rigel Pharmaceuticals since 2023. Most investors ignore investment opportunities in small biopharmaceutical companies. That makes sense on its face, since the vast majority of these companies are clinical stage operations with no earnings or even revenue. But in doing so, these investors miss the handful of companies at the intersection of FDA approved assets and very small market caps, which we have seen enable attractive investment opportunities many times in our 20 years of investing in this asset class. Achieving FDA approval generally requires hundreds of millions of dollars, and it typically buys years of patent protection before generics or biosimilars arrive. FDA approval is therefore a major value inflection. The few investors that do invest in small biopharmaceutical companies often "sell the news" of an FDA approval, unwilling to hold investments through a launch cycle that will be less exciting than the approval itself. We take the other side. The perception of commercial stage biopharmaceutical businesses can improve dramatically within a few years as companies product strong revenues and a clear path to earnings.
In the case of Rigel Pharmaceuticals, the company already had multiple FDA-approved therapies in 2023 and was on its way to generating cash flow. Then, in February 2024, Rigel agreed to buy the US rights to Gavreto, a treatment for non small cell lung cancer and thyroid cancer, from Blueprint Medicines. Blueprint had previously partnered the commercialization of Gavreto with European pharma giant, Roche, but Roche terminated the partnership in 2023, a decision we believe reflects the drug's small scale relative to Roche's business. For context, Roche's 2023 revenue was roughly $65B, so Gavreto's $28M of 2023 U.S. sales was a rounding error. Rigel paid Blueprint $15 million upfront, plus tiered royalties and potential future milestones. Rigel began selling Gavreto in June 2024, and sales reached a run rate of about $40 million a year within the first year. Based on our own margin estimates, we believe Rigel recouped its upfront payment within a year of launch. Notably, patents covering Gavreto run from 2036 to 2041, therefore we expect the company to extract another 10-15 years of durable profit from this asset via its patent protection, depending on when competition emerges. In any event, this is a case where a large cap company walked away from a valuable commercial stage asset due to immateriality creating an attractive investment opportunity for a much smaller company.
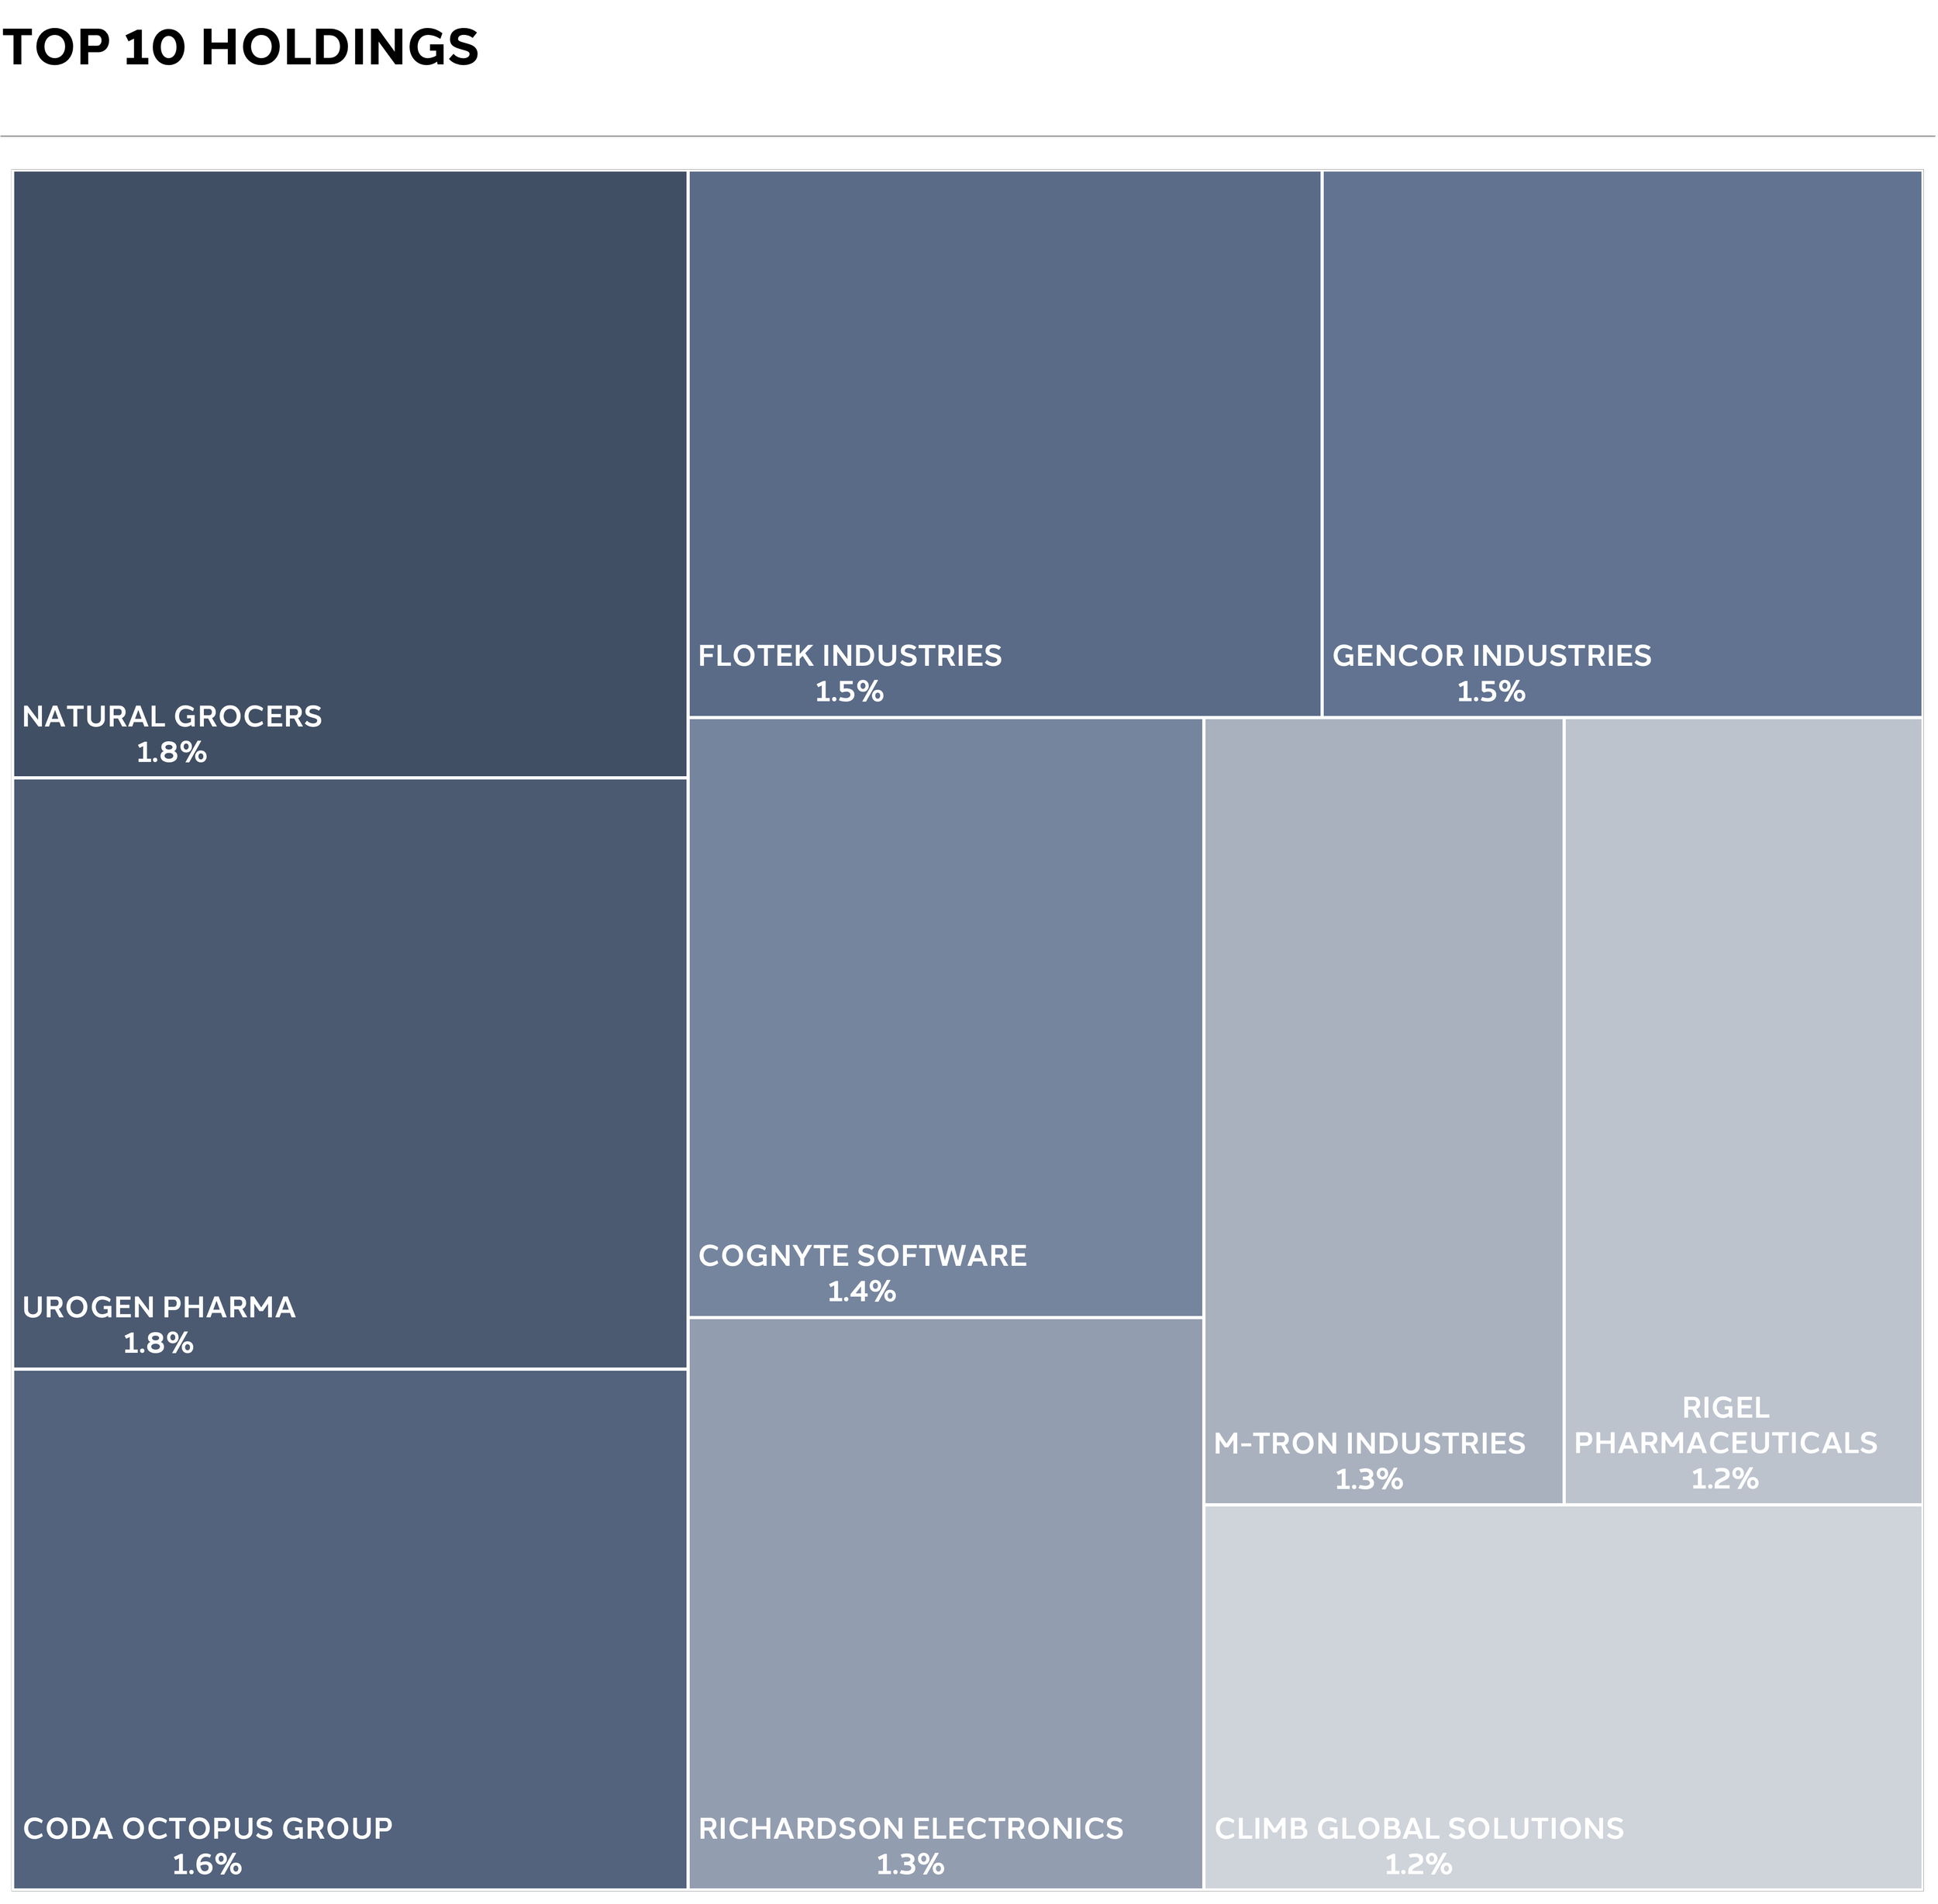
The Fund's current largest holdings are companies our investment team believes will benefit from niche structural inefficiencies, as in Pennant and Rigel. Conventional wisdom holds that the best opportunities are great companies at reasonable prices. Because small public equities are generally overlooked and not owned by traditional strategies including ETFs, companies can from time to time trade at reasonable prices, which reduces our job, to a degree, to simply finding good companies. In 20 years investing in this universe, we have found recurring structural sources of quality at discounted valuations, including the "too small to matter" inefficiency.
Position Changes
-
New positions are initiated in the fund when they are attractive per LuxβetaTM (quantitative review) and validated through LuxαlphaTM (qualitative analysis). The fund initiated new positions in the following companies during the quarter:
ABEONA THERAPEUTICS
AMERISAFE
BARNES & NOBLE EDUCATION
BUILD-A-BEAR WORKSHOP
CARTER'S
GLOBAL SELF STORAGE
INVESTORS TITLE COMPANY
JOHN B. SANFILIPPO & SON
NATURE'S SUNSHINE PRODUCTS
NEPHROS
NORTHRIM BANCORP
OPUS GENETICS
PHATHOM PHARMACEUTICALS
PRECIPIO
PURE CYCLE CORPORATION
REPOSITRAK
SIFCO INDUSTRIES
SMITH-MIDLAND CORPORATION
SPOK HOLDINGS
SPROUT SOCIAL
TURNING POINT BRANDS
ULTRAGENYX PHARMACEUTICAL
VIRIDIAN THERAPEUTICS
-
Positions are sold from the fund when their LuxβetaTM profile deteriorates, the company develops significant off model, appreciates out of the micro cap asset class, or the company is acquired. The fund sold positions in the following companies during the quarter:
BOWHEAD SPECIALTY HOLDINGS (received acquisition offer)
CIVEO
EGAIN
GAIA
HARMONY BIOSCIENCES
INSPIRE MEDICAL SYSTEMS
JAKKS PACIFIC
KARAT PACKAGING
KINIKSA PHARMACEUTICALS
LANTRONIX
MITEK SYSTEMS
NATIONAL RESEARCH CORPORATION
NIAGEN BIOSCIENCE
NPK INTERNATIONAL
SANARA MEDTECH (received acquisition offer)
SELECT WATER SOLUTIONS
SIMILARWEB
SONO-TEK
TECOGEN
TRAVELZOO
TUCOWS
VIRCO MFG
VOYAGER THERAPEUTICS
XERIS BIOPHARMA
Performance Summary
Let’s keep in touch.
ⁱUnaudited return net of fees.
Gurnee Group, LLC (the “General Partner”) is not registered as an investment adviser with the Securities and Exchange Commission. However, the General Partner is registered as an investment adviser with the Department of Commerce of the State of Ohio. The limited partnership interests (the “Interests”) in Gurnee Group Lux Fund, LP (the “Fund”), are offered under a separate private offering memorandum (the “Offering Memorandum”), have not been registered under the Securities Act of 1933, as amended (the “Securities Act"), nor any state's securities laws, and are sold for investment only pursuant to an exemption from registration with the SEC and in compliance with any applicable state or other securities laws. Interests are subject to restrictions on transferability and resale and may not be transferred or resold except as permitted under the Securities Act and applicable state securities laws. Investors should be aware that they could be required to bear the financial risks of this investment for an indefinite period of time.
This presentation is being furnished to you on a CONFIDENTIAL basis to provide preliminary summary information regarding an investment in the Fund managed by the General Partner and may not be used for any other purpose. Any reproduction or distribution of this presentation or accompanying materials, if any, in whole or in part, or the divulgence of any of its contents is prohibited. The information set forth herein does not purport to be complete and no obligation to update or otherwise revise such information is being assumed. It is meant to be read in conjunction with the Offering Memorandum prepared in connection herewith, and does not constitute an offer to sell, or a solicitation of an offer to buy, by anyone in any jurisdiction in which such an offer or solicitation is not authorized or in which the making of such an offer or solicitation would be unlawful. The information contained herein does not purport to contain all of the information that may be required to evaluate an investment in the Fund. The information herein is qualified in its entirety by reference to the Offering Memorandum, including, without limitation, the risk factors therein.
A prospective investor should only commit to an investment in the Fund if such prospective investor understands the nature of the investment and can bear the economic risk of such investment. THE FUND IS SPECULATIVE AND INVOLVES A HIGH DEGREE OF RISK. The Fund may lack diversification, thereby increasing the risk of loss. The Fund's performance may be volatile. There can be no guarantee that the Fund's investment objectives will be achieved, and the investment results may vary substantially from year to year or even from month to month. AS A RESULT, AN INVESTOR COULD LOSE ALL OR A SUBSTANTIAL AMOUNT OF ITS INVESTMENT. In addition, the Fund's fees and expenses may offset its profits. There are restrictions on withdrawing and transferring interests from the Fund. In making an investment decision, you must rely on your own examination of the Fund and the terms of the Offering Memorandum and such other information provided by the General Partner to you and your tax, legal, accounting or other advisors. The information herein is not intended to provide, and should not be relied upon for, accounting, legal, or tax advice or investment recommendations. You should consult your tax, legal, accounting or other advisors about the matters discussed herein. The Fund's ability to achieve its investment objectives may be affected by a variety of risks not discussed herein. Please refer to the Offering Memorandum for additional information regarding risks and conflicts of interest.
No representations or warranties of any kind are made or intended, and none should be inferred, with respect to the economic return or the tax consequences from an investment in the Fund. No assurance can be given that existing laws will not be changed or interpreted adversely. Prospective investors are not to construe this presentation as legal or tax advice. Each investor should consult his or its own counsel and accountant for advice concerning the various legal, tax, ERISA and economic matters concerning his or its investment.
No person other than the General Partner, and its Principal, has been authorized to make representations, or give any information, with respect to these membership interests, except the information contained herein, and any information or representation not expressly contained herein or otherwise supplied by the Principal in writing must not be relied upon as having been authorized by the General Partner or any of its members. Any further distribution or reproduction of these materials, in whole or in part, or the divulgence of any of its contents, is prohibited.
An investment in the Fund has not been approved by any U.S. federal or state securities commission or any other governmental or regulatory authority. Furthermore, the foregoing authorities have not passed upon the accuracy, or determined the adequacy, of this document, the Offering Memorandum or limited partnership agreement associated with the Fund. Any representation to the contrary is unlawful.
Certain information contained in this document constitutes “forward-looking statements” which can be identified by use of forward-looking terminology such as “may,” “will,” “target,” “should,” “expect,” “attempt,” “anticipate,” “project,” “estimate,” “intend,” “seek,” “continue,” or “believe” or the negatives thereof or other variations thereon or comparable terminology. Due to the various risks and uncertainties, actual events or results in the actual performance of the Fund may differ materially from those reflected or contemplated in such forward-looking statements. The General Partner is the source for all graphs and charts, unless otherwise noted.
This document may present past performance data regarding prior/other investments, funds, and/or trading accounts managed by the General Partner and/or the Principal. This is presented solely for explanatory purposes. The Fund may face risks not previously experienced or anticipated by the General Partner and/or Principal, and therefore, prospective investors should evaluate the Fund on its own merits. Furthermore, there is no guarantee the General Partner and/or Principal will be able to replicate the mandate, strategy, portfolio construction and risk management parameters reflected in their prior performance data. Market factors and unforeseen circumstances both internally and externally may result in a wide deviation from the returns reflected in the prior performance data, and there is no guarantee the General Partner and/or Principal will be able to avoid and/or remediate such internal and external factors.
Furthermore no representation or warranty can be given that the estimates, opinions or assumptions made herein will prove to be accurate. Any such estimates, opinions or assumptions should be considered speculative and are qualified in their entirety by the information and risks disclosed in the Offering Memorandum. The assumptions and facts upon which any estimates or opinions herein are based are subject to variations that may arise as future events actually occur. There is no assurance that actual events will correspond with the assumptions. Potential investors are advised to consult with their tax and business advisors concerning the validity and reasonableness of the factual, accounting and tax assumptions. Neither the General Partner nor any other person or entity makes any representations or warranty as to the future profitability of the Fund.
PAST PERFORMANCE IS NOT INDICATIVE OR A GUARANTEE OF FUTURE RESULTS.
This document may also present “sample holdings” or “case studies” of a type of asset(s) the Fund may invest in or are expected to be typical of its holdings. Such “sample holdings” are not currently holdings of the Fund and are presented solely for explanatory purposes. Prospective Investors should not assume that such “sample holdings” will actually be purchased by the Fund when determining whether to make an investment in the Fund.